September 21, 2026
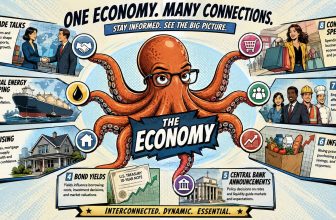
It was one of those stretches where several genuinely big stories landed within days of each other — and any one of them could (potentially) turn into something much bigger over the next few months, and furthermore, could work its way all the way down to your mortgage rate. Here’s a quick recap of what actually happened, and where it leaves your mortgage heading into the Bank of Canada’s next decision (Oct 28, 2026).
1. Canada’s Investment Pitch (Right After a Very Different Headline)
Canada rolled out a full-court press this week to attract foreign investment. Prime Minister Carney’s message at the Canada Investment Summit was simple: “Canada has what the world wants.” The catch — that pitch landed the same week a report came out on the economic implications of national separation. Confusing timing for anyone watching from the outside, but then again, you would think serious investors would care more about the fundamentals rather than a stray headline.
2. The Productivity Mega Deduction — A Potentially Big One
The real story underneath the investment pitch was a new tax measure called the Productivity Mega Deduction. It lets businesses write off a much larger share of their capital spending immediately, instead of over several years — a change that could cut the effective tax rate on new investment nearly in half. It’s a fairly candid acknowledgment, even if unspoken, that Canada has struggled to attract business investment for the better part of a decade. If it holds up as designed, this is the kind of policy shift that could genuinely move the needle.
3. A Surprise Offer From the EU
Out of nowhere, Canada also received an offer from the European Union: a first-ever “associate membership.” Details are thin — it still needs to be structured and approved by Parliament — so it’s genuinely too early to know whether this becomes a major development or quietly fades. Worth watching closely over the coming months.
4. The Fed Hiked — First Time in Three Years
Meanwhile, the U.S. Federal Reserve raised its policy rate for the first time in three years, a clear signal it’s growing concerned about inflation again south of the border. Moves like this tend to shape the broader conversation the Bank of Canada is having about its own rate path.
5. The One That Actually Touches Your Wallet: Core Inflation
This is where it gets directly relevant to you. The Bank of Canada’s own recent messaging shows growing concern about core inflation — inflation that has spread beyond a single cost driver into a broader range of goods and services. Higher diesel and shipping costs have quietly started showing up in other consumer prices, including groceries. The Bank isn’t only tracking headline inflation anymore — it’s watching whether cost pressures are broadening, which is a much harder trend to reverse once it takes hold.
Here’s the general consensus heading into the next decision: the Bank’s next announcement is October 28th, and the current expectation is that it holds steady, keeping prime rate at 4.45%. The reasoning is straightforward — the economy is considered too fragile right now to absorb a rate hike. But if core inflation keeps climbing between now and then, that assumption could shift quickly, and an earlier-than-expected hike becomes a real possibility. There are two Bank of Canada rate announcements left in 2026: October 28th and December 9th.
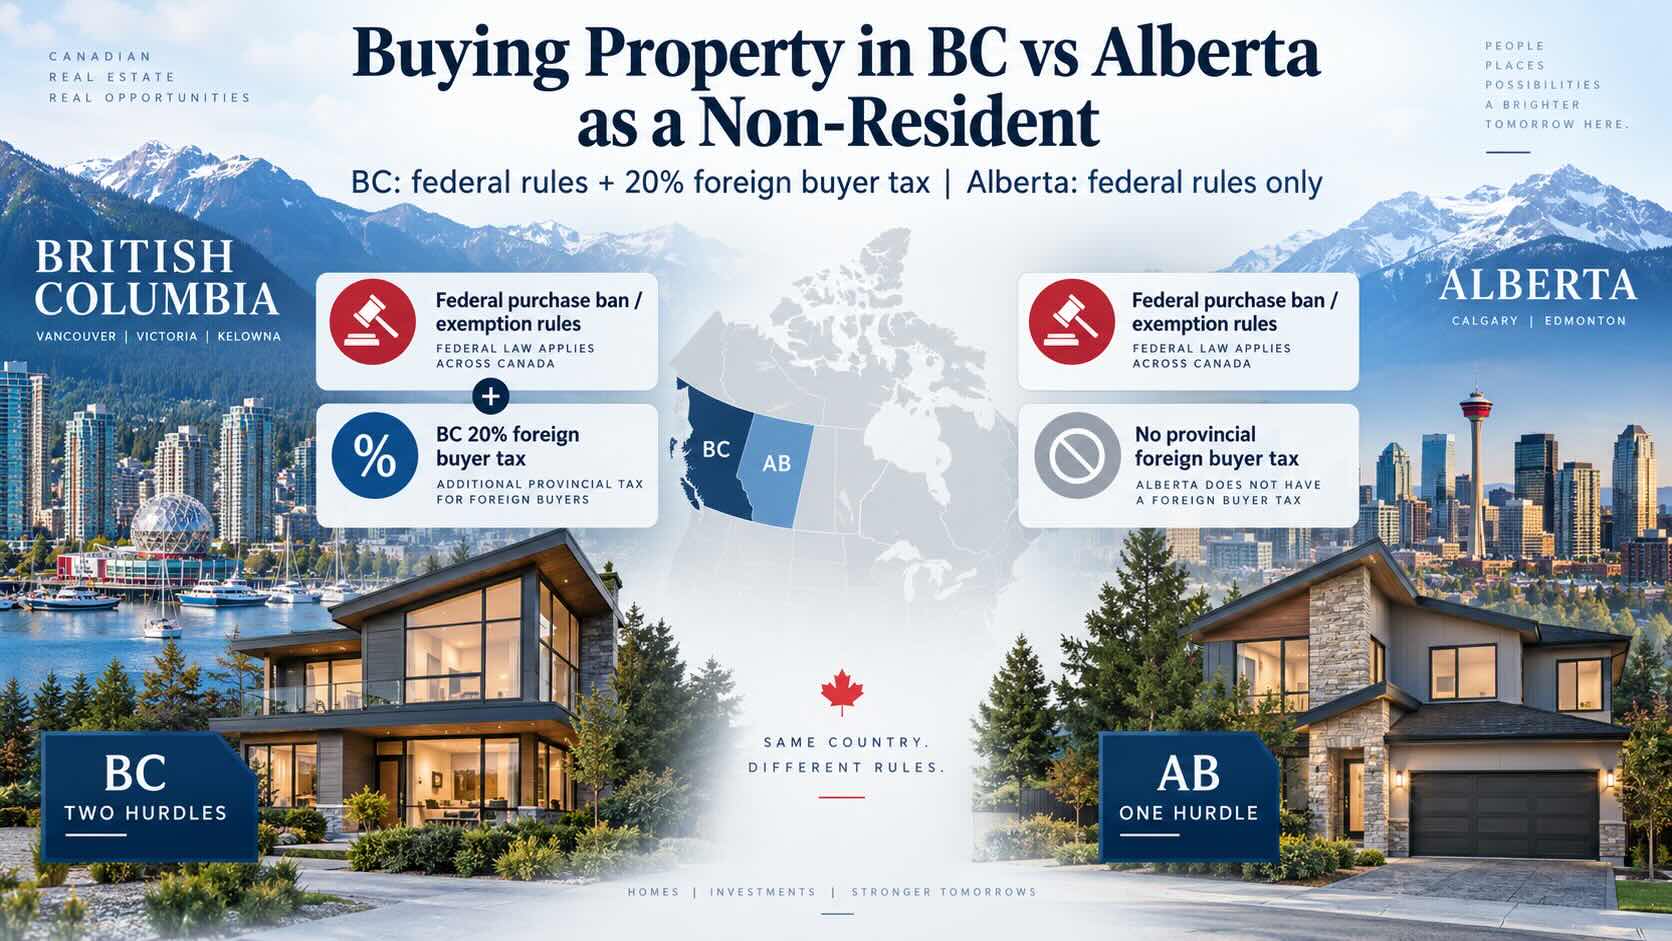
This applies the same way whether you’re in Vancouver or Calgary — the Bank of Canada sets one national rate, so the renewal math works out identically no matter which province you’re in.
The Recap
A confusing but potentially significant investment pitch. A tax break that could be a genuine turning point. A European offer that could be huge or could go nowhere. A Fed that’s clearly nervous. And a Bank of Canada decision on October 28th that’s currently expected to hold — but isn’t locked in. Several of these stories could still swing in a meaningful direction between now and December.
A rising core inflation reading is the single number worth watching most closely between now and the October decision. If you’re on a variable-rate mortgage or coming up on a renewal, this is exactly the kind of window where it pays to have someone tracking the data with you.
Ready to talk about your mortgage?
I’m Marko Gelo, a dually licensed mortgage broker in BC and Alberta. Call or text me at 604-800-9593 — one application, one credit check, and access to Canada’s top lenders.
Connect with Marko
Mortgage strategy, calculators, and direct access—without the bank-branch waiting room.
604-800-9593 ph1 | 403-606-3751 ph2 | mortgages@markogelo.ca
Download the Mortgage App for calculators and planning tools, or subscribe to get future posts delivered directly to your inbox.